

 Share


Bonus TL;DR
- DraftKings shares fell 22.3% due to lower earnings estimates and planned $200M–$300M investments in prediction markets for 2026.
- DraftKings maintained its 2026 revenue target of $6.5B–$6.9B despite rising regulatory uncertainty and growing competitive pressure.
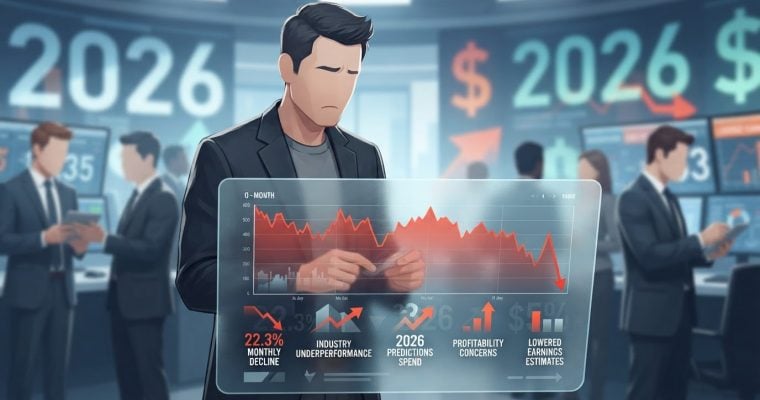
DraftKings shares fell 22.3% over the past month, a steeper drop than the 7% decline for the broader gaming industry, as investors weighed lower earnings estimates and the company’s planned spending on predictions in 2026.
The selloff matters because it comes even though DraftKings kept its 2026 revenue guidance of $6.5 billion to $6.9 billion and adjusted EBITDA guidance of $700 million to $900 million in place. The debate for investors is whether the stock’s recent decline creates value or reflects deeper concerns around profitability, competition, iGaming performance, and regulatory uncertainty.
Guidance holds, but earnings estimates move lower
According to the source report, DraftKings plans to invest an incremental $200 million to $300 million in its Predictions business in 2026. That spending has added to concerns about near-term profitability, particularly as the company also faces competitive pressure and weaker iGaming trends.
At the same time, analyst expectations have moved down. Over the past 60 days, the Zacks consensus estimate for DraftKings’ 2026 earnings fell to $0.90 per share from $1.03. The 2027 earnings estimate also slipped to $1.75 from $1.78.
The source also pointed to unresolved regulatory questions around prediction markets. It did not specify which jurisdictions are included in that opportunity, and it noted uncertainty over how DraftKings’ predictions business will be regulated in different states.
Valuation looks cheaper, but not the cheapest in the group
DraftKings’ forward 12-month price-to-sales ratio was cited at 1.25x. That is above Caesars Entertainment’s 0.49x and Wynn Resorts’ 0.99x, even after the recent pullback in DraftKings shares.
The source framed that as a valuation discount relative to DraftKings’ own recent levels, but not necessarily enough to offset concerns about execution and spending. It also noted that DraftKings carries a Zacks Rank #5 (Strong Sell).
For the gambling industry, the report highlights a tension that extends beyond DraftKings’ share price: operators are still pursuing new growth areas such as predictions while also facing pressure to show margin discipline in sports betting and iGaming.
What comes next will likely center on whether DraftKings can scale its predictions offering without further denting profitability, and whether its core sportsbook and iGaming business can stabilize enough to support the company’s 2026 targets.
Source: As reported by tradingview.com.